Loan Management Software for Africa: MFIs, SACCOs, and Device Financing Companies
- Why African Lenders Need Purpose-Built Tooling
- Field Agent Collections for Branch and Rural Operations
- WhatsApp and SMS Repayment Reminders
- Device Financing and Android Device Locking (Superkey)
- Digital Payment Collection
- Compliance and Audit Trails for SACCO Regulators
- Multi-Currency Support
- Why Freebird for African Lenders
- Request a Live Demo
- Frequently Asked Questions
Running a lending operation in Africa in 2026 means dealing with tighter regulation, more demanding borrowers, and field teams that need to work reliably even when the data signal disappears. Whether you manage a SACCO in Kenya, a Tier 4 MFI in Uganda, or a mobile-device financing company in Ghana or Nigeria, generic loan management software built for Western markets rarely fits how you actually work.
This page covers what dedicated loan management software for Africa looks like, which features matter most for your segment, and how Freebird is built to serve lenders across the continent managing between 50 and 2,000 active borrowers.
Request a Live Demo at usefreebird.com
Why African Lenders Need Purpose-Built Tooling
The regulatory and operational context in Africa is genuinely distinct. Kenya's SASRA (Sacco Societies Regulatory Authority) requires SACCOs to maintain detailed member loan records, produce audit-trail documentation, and demonstrate compliance with prudential guidelines. Uganda's Tier 4 Microfinance Institutions and Money Lenders Act places similar obligations on smaller MFIs and money lenders — licensed entities must keep structured loan books and submit periodic returns. The Central Bank of Kenya's Digital Credit Provider licensing framework adds another layer, requiring digital lenders to demonstrate responsible lending practices, data governance, and transparent disclosure.
None of that is manageable on a spreadsheet once your portfolio crosses a few hundred borrowers. You need software that logs every disbursement, repayment, fee, and agent interaction with a timestamp and an audit trail a regulator can actually read.
The operational realities are just as demanding. Your field agents may collect repayments in cash at a borrower's home or market stall. Your borrowers may not have consistent internet access, but almost all of them use WhatsApp. Your device-financing customers have collateral sitting in their hands, and you need a way to enforce repayment without going through a court process.
Purpose-built tooling addresses all of this. Generic software does not.
Field Agent Collections for Branch and Rural Operations
Most African MFIs and SACCOs do not operate like a fintech app where borrowers self-serve online. Collections happen in the field. A loan officer visits a group, records repayments, handles exceptions, and reports back to the branch.
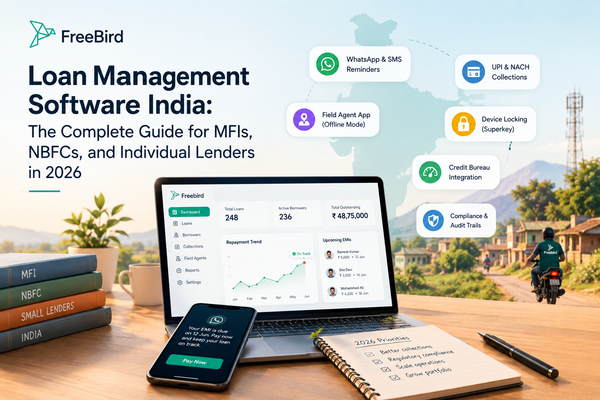
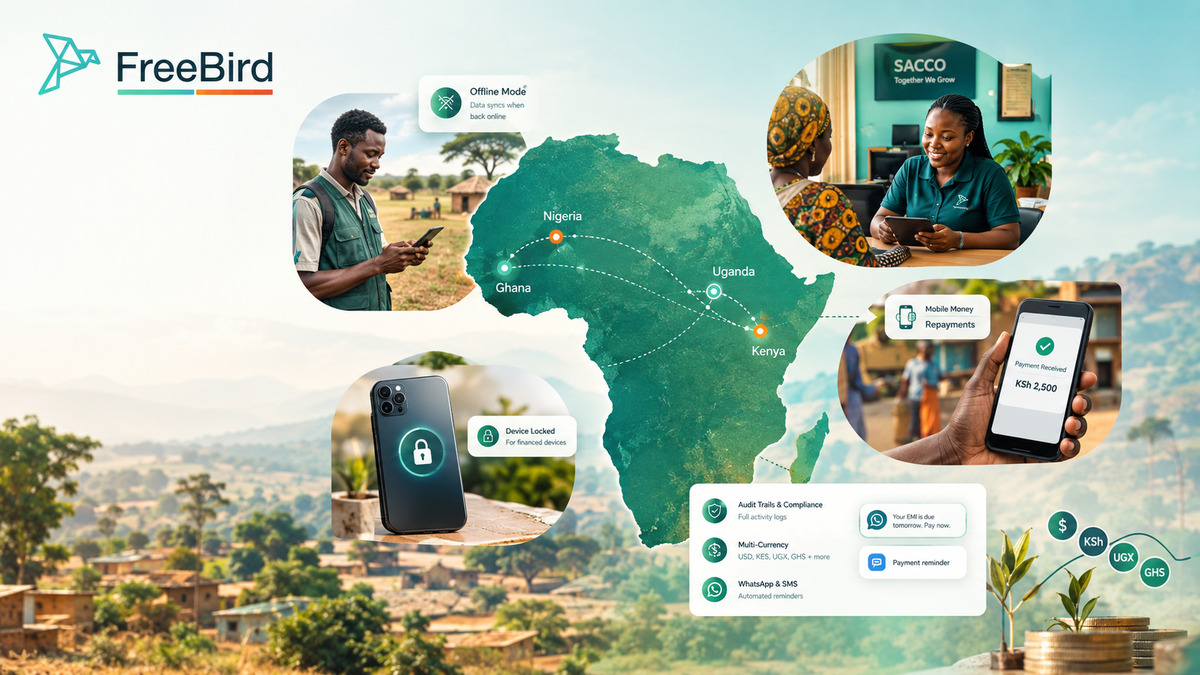
Freebird's Android field agent app is built for exactly this workflow. Agents can view their assigned borrower list, record repayments, log visit notes, and capture signatures or photos — all from a mobile device. Critically, the app works offline. If your agent is in a rural area with no data signal, the app queues all activity locally and syncs automatically when connectivity returns.
This matters because coverage gaps are real across much of Sub-Saharan Africa. Software that requires a live internet connection to record a repayment will fail your team in the field. Freebird does not.
Back at the branch or head office, every agent action is logged with a timestamp and tied to the agent's account — creating the kind of audit trail that satisfies SASRA and Tier 4 MFI requirements without any manual reconciliation.
WhatsApp and SMS Repayment Reminders
Smartphone penetration in many African markets is high, but data reliability is not. WhatsApp, however, is deeply embedded in how people communicate — even on low-data connections — and it is often the first messaging channel borrowers actually respond to.
WhatsApp-native automation is built into the core of Freebird, not bolted on as a third-party integration. You configure reminder schedules and the platform handles the rest: automated repayment reminders go out at set intervals before and after a due date, overdue notices, payment confirmations, and disbursement alerts — all without manual effort from your team.
Because it is a core part of the platform rather than an add-on, it works reliably at scale and does not require a separate tool or a developer to maintain. For borrowers who are not on WhatsApp, SMS fallback ensures no one slips through. Fewer missed reminders means fewer missed payments, which directly improves your collection rate without adding headcount.
Request a Live Demo at usefreebird.com
Device Financing and Android Device Locking (Superkey)
Device financing is one of the fastest-growing lending segments in Africa. Mobile shops, consumer durable retailers, and fintech lenders are offering smartphones, tablets, and other devices on credit — often to first-time borrowers with no formal credit history.
The challenge is enforcement. If a borrower stops paying, you have no easy legal recourse, and the device is already in their hands.
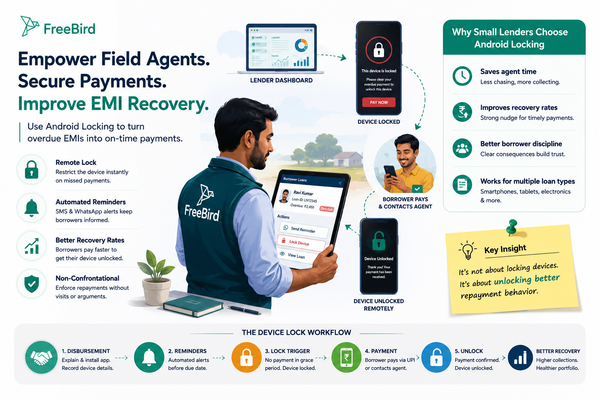
Freebird's Superkey feature is a direct answer to this problem. Superkey is an Android device-locking capability built into the Freebird platform. When a borrower misses a payment, the system automatically locks the financed device, rendering it unusable until the payment is made. When the payment clears, the device unlocks — no manual intervention required.
The lock and unlock cycle is tied directly to the loan repayment schedule in Freebird, so your team does not need to get involved. The borrower receives a WhatsApp notification explaining why the device is locked and what they need to do to restore access.
Superkey is available in Africa and India and is one of the very few features of its kind available in a commercial loan management platform at this price point. For any lender running a device or mobile-financing portfolio, it fundamentally changes the risk profile of the product.
Digital Payment Collection
African markets are increasingly moving toward mobile money and digital payment rails. M-Pesa in Kenya, MTN Mobile Money in Uganda and Ghana, and bank transfer integrations are all part of how borrowers repay today.
Freebird supports digital payment collection workflows that fit these local rails. Repayments recorded through the field agent app or through borrower-initiated mobile money transfers are logged automatically against the correct loan account, reducing manual reconciliation and the risk of misposting.
For lenders who also operate in India, Freebird's UPI and NACH auto-mandate stack handles direct debit collection natively. The platform is built to support multiple payment contexts across geographies — which matters if your organization already operates across borders or is planning to expand.
Compliance and Audit Trails for SACCO Regulators
SASRA-regulated SACCOs in Kenya must maintain member loan records, produce loan schedules, and demonstrate that interest calculations and fee disclosures meet regulatory standards. Tier 4 MFIs in Uganda face similar documentation requirements under the Tier 4 Act.
Freebird is compliance-friendly by design. Every loan action — disbursement, repayment, fee adjustment, waiver, or restructure — is logged with a timestamp and a user attribution. You can pull a full audit trail for any loan at any time, which is exactly what a regulator or external auditor needs to see.
Loan schedules, repayment histories, and portfolio-level reports are all generated from the same system that runs your day-to-day operations. There is no separate reporting tool to maintain and no manual export required. That reduces the compliance burden on your team and makes regulatory submissions faster and less error-prone.
Multi-Currency Support
If you operate across multiple African markets — or if your funding is denominated in USD or EUR while your loans are disbursed in local currency — multi-currency support is not optional. Freebird handles multi-currency loan books, allowing you to manage portfolios in KES, UGX, GHS, NGN, or other currencies within the same platform.
This is particularly relevant for international NGOs and development finance-backed MFIs that report to funders in one currency while lending in another.
Why Freebird for African Lenders
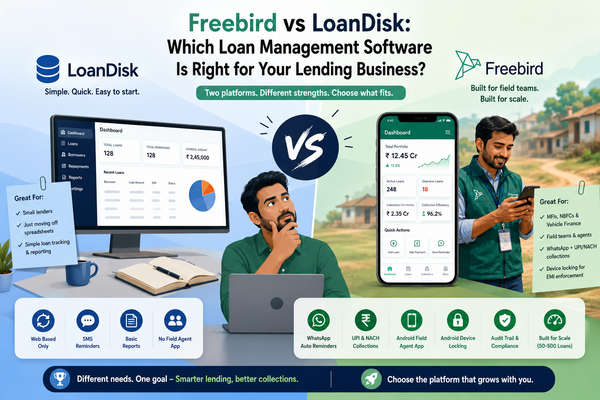
Freebird is built for MFIs, SACCOs, and device financing companies managing between 50 and 2,000 borrowers — and it is positioned as a cost-effective alternative to platforms like Lendsqr and LoanDisk. The platform is mobile-first, which reflects how lending actually works in Africa, not how it works in a Western bank.
The combination of an offline-capable Android field agent app, WhatsApp-native automation, and Superkey device locking is not available in most competing platforms at a comparable price point. These are not features that were added as afterthoughts — they are the core of what Freebird was built to do.
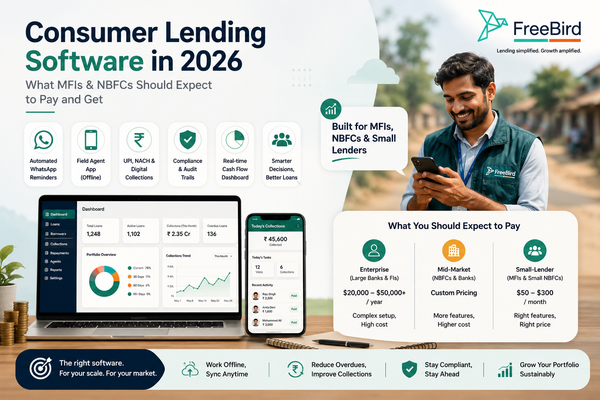
For lenders with tight budgets who cannot afford enterprise software but need more than a spreadsheet, Freebird is designed to fill that gap. Current plans and pricing are available at usefreebird.com.
Request a Live Demo
If you manage loans for an MFI, SACCO, or device financing company in Africa and want to see how Freebird handles your specific workflow — field collections, WhatsApp reminders, device locking, compliance reporting — the best next step is a live demo.
Request a Live Demo at usefreebird.com
Frequently Asked Questions
Does Freebird work for SACCOs regulated by SASRA in Kenya?
Yes. Freebird's audit-trail logging and compliance-friendly reporting are designed to support the documentation requirements that SASRA-regulated SACCOs need to maintain. Every loan action is timestamped and attributed to a user, making regulatory submissions and audits straightforward.
Can field agents use Freebird without an internet connection?
Yes. The Freebird Android field agent app works fully offline. Agents can record repayments, log visit notes, and manage their borrower list without a live data connection. All activity syncs automatically when the device reconnects.
What is Superkey and how does it work for device financing?
Superkey is Freebird's Android device-locking feature. It ties directly to the loan repayment schedule — if a borrower misses a payment, the financed device is locked automatically, and when the payment clears, it unlocks without any manual intervention from your team. It is available for lenders in Africa and India.
Does Freebird support mobile money payment collection in Africa?
Yes. Freebird supports digital payment collection workflows that accommodate mobile money repayments. Payments are logged automatically against the correct loan account, reducing manual reconciliation.
Can Freebird handle loans in multiple African currencies?
Yes. Freebird supports multi-currency loan books including KES, UGX, GHS, NGN, and other currencies within the same platform — useful for organizations operating across multiple markets or reporting to funders in a different currency.
How does WhatsApp automation work in Freebird?
WhatsApp-native automation is built into the core of Freebird, not added as a third-party integration. You configure reminder schedules and the platform sends repayment reminders, overdue notices, and payment confirmations to borrowers via WhatsApp automatically — no manual effort required from your team.
Is Freebird affordable for small MFIs with tight budgets?
Freebird is built specifically for lenders managing 50 to 2,000 borrowers and is positioned as a cost-effective alternative to larger platforms like Lendsqr and LoanDisk. Specific pricing is available at usefreebird.com.